Loading page…
Place CSR money you can account for later.
Find NGOs with a clear registration status, release each payment against milestone evidence, and keep the pack your finance and audit teams will ask for.
The obligation you are already under
- Any 1 of 3
- tests brings a company in: net profit of ₹5 crore, net worth of ₹500 crore, or turnover of ₹1,000 crore, in the year before
- 2%
- of average net profit over the last three years is the least a company must spend
- 30 days
- from year end to move unspent money on an ongoing project into the Unspent CSR Account, then three years to spend it
- 6 months
- from year end to pay other unspent money into a fund named in Schedule VII
- CSR-1
- registration every implementing agency needs, along with 12A and 80G tax registrations, before it can receive CSR money
- ₹10 crore
- average yearly CSR obligation at which a company must have its projects of ₹1 crore or more assessed by an independent agency
- 2x
- the unspent amount, or ₹1 crore if that is less, is the company's penalty for not moving it on time. Each officer in default pays one-tenth of the unspent amount, or ₹2 lakh if that is less. The transfer is still due.
- 2 places
- to report: the annual CSR report goes in the Board's Report, and the committee, policy and approved projects go on the company's website
Companies Act 2013, Section 135(1)
Companies Act 2013, Section 135(5)
Companies Act 2013, Section 135(6)
Companies Act 2013, Section 135(5)
Companies (CSR Policy) Rules, Rule 4
Companies (CSR Policy) Rules, Rule 8(3)
Companies Act 2013, Section 135(7)
Companies (CSR Policy) Rules, 8 and 9
What your CSR team stops doing by hand
Diligence with a visible status
Each NGO profile shows what the NGO has claimed and what Peeple has checked at the register that issued it, with the date. Nothing is shown as checked before a person has looked.
Fund against milestones, not against trust
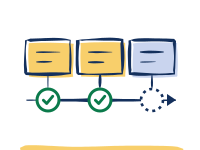
Agree the milestones in an MOU, then release each payment once its evidence is accepted. Money for later milestones stays with you, and a rejected milestone stays on the record.
The board breakdown, without rebuilding it
Your obligation, what is spent, what is set off from earlier years and what is unspent, for each financial year, with every project mapped to its Schedule VII head.
The filing pack, ready for your auditor
Utilisation certificates, evidence, the CFO certificate and the data for Form CSR-2 kept against each project. Whether a particular arrangement qualifies is still your CA's call, and we will not pretend otherwise.
Tell us what your CSR budget has to do this year.
We will come back with which NGOs fit, what it would cost, and what your auditor would get at the end of it.